Work With a Health Insurance Broker Who Knows Tampa, FL
Tampa is large enough that the carrier field reshuffles from South Tampa to New Tampa, yet personal enough that nobody should be decoding plan documents alone at midnight. A health insurance broker based right here on East Hillsborough Avenue gives you someone who lays every carrier side by side and turns the network-tier jargon into plain dinner-table words. When people search for health insurance brokers near me, what they are really after is exactly this kind of local read.
Whether a particular plan is even open to you hinges on your precise Tampa address, the carriers writing in that ZIP, and the enrollment window your household qualifies to use right now — all of which an independent health insurance agent confirms before you sign anything.
The Three Places a Tampa Plan Decision Usually Breaks Down
You are not stuck because you missed something obvious. The Tampa carrier field rewards insiders and quietly leaves everyone else guessing, and most households that reach a health insurance broker have been snagged by one of these three things first.
Carrier Footprints That Shift Block to Block Across Tampa
A plan that covers Tampa General beautifully in South Tampa might run thin once you cross the river into Town ‘N’ Country. Specialist networks change at the county line. Formularies reset every January. Open enrollment closes whether you are ready or not.
The Sleep-Lost Feeling You Will Pick the Wrong Card
You can stare at the same four plans for two hours and still feel like a coin toss. The worry is not paranoia — one wrong assumption can drop a pediatric specialist into out-of-network billing, or push a maintenance prescription up a formulary tier that reshapes your out-of-pocket picture overnight.
A Bay-Area City This Big Should Not Make Coverage Feel This Small
Tampa runs on professionals, military families, port workers, freelancers, and small business owners who already carry plenty. Protecting your household should not be the most stressful errand on the calendar. What you deserve is a veteran ally in the chair next to yours, one who has navigated this exact maze for years.
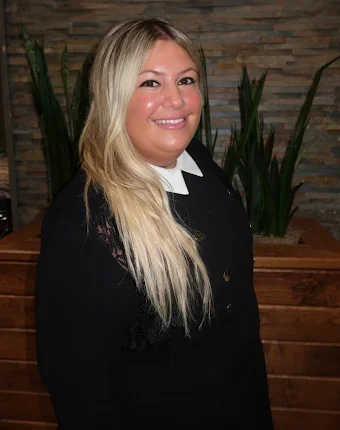
Sofia, the Tampa Health Insurance Advisor Who Reads Carrier Fine Print for a Living
Her Days Look a Lot Like Yours, Down to the I-275 Slog
Every week Sofia sits with Tampa neighbors holding the exact questions on your mind right now — a Westshore parent watching a corporate plan jump at renewal, a Seminole Heights freelancer trying to make 1099 income and an HSA land in the same month, a separating service member at MacDill mapping what follows TRICARE, a Davis Islands retiree pairing Medicare with a supplement that holds at Tampa General. None of these situations stand between a household and a plan that fits, and each one is the kind of thing an independent health insurance agent untangles for a living.
The pace follows you, not a quota. A recommendation arrives once your questions are answered, never before. And enrollment waits until you ask for it — the way working with a real advisor should feel.
Why Tampa Neighbors Hand Her the Coverage Decision
- A licensed health insurance agent operating from the 5701 E Hillsborough Avenue office, serving the full Tampa carrier field.
- A finance background that keeps premiums, deductibles, and the whole out-of-pocket picture anchored to what your household can genuinely spend.
- A health insurance broker appointed across multiple carriers — never captive to a single brand.
- Hundreds of Tampa-area households reviewed across South Tampa, Westshore, New Tampa, the USF corridor, and the MacDill area.
- Client ratings averaging 5.0 stars, and a direct number a real person still answers once coverage begins.
Three Phone Calls That Move Tampa Coverage From Question Mark to Card in Hand
The whole path looks fuzzy from the outside. Here it is in three short conversations — no surprise paperwork, no hidden middle step.
Brief Sofia on the Tampa Household Picture
Names on the policy, the providers you want to keep, the prescriptions you fill, and a comfortable monthly range that does not crowd out rent, the kids’ activities, or the mortgage on Bayshore. One call with your health insurance broker, plain language, no commitment.
Weigh the Carriers Actually Active in Your ZIP
Look at HMO, EPO, PPO, and POS options that genuinely cover your address — provider participation confirmed, formulary checked against your medication list, and the real monthly and out-of-pocket numbers laid out side by side instead of buried in carrier marketing.
Activate the Plan With Your Doctor List Confirmed
Submit inside the enrollment window that fits your situation, get a first-month orientation on how to use the card at Tampa General or AdventHealth, and walk away with a direct line to Sofia when something comes up months later.
Hand the Plan Comparison Off and Get Your Evenings Back
The first consultation is free and ends with a written recommendation built around your Tampa household — whether you enroll in the same conversation or take a week to think it over with everyone who needs a say.
Coverage Lines a Tampa Health Insurance Broker Opens With You First
Plan Types
CoreCoverage Needs
PopularThe Tampa Week You Get Back Once Coverage Is Sorted Right
A South Tampa parent drops their child at a Hyde Park pediatrician for a follow-up visit, hands over the insurance card, and pays the exact cost-share she already knew about on the drive over. A Seminole Heights graphic designer working out of a Florida Avenue coffee shop spends ten minutes refilling a maintenance prescription instead of an hour fighting a formulary surprise. A separating service member finishing his last week at MacDill activates civilian coverage that begins the day TRICARE ends, with the family pediatrician in Carrollwood already verified in-network. A USAA contractor in Westchase contributes to an HSA that actually pairs with the plan he picked, instead of finding out in March that the pairing never worked.
A well-fit plan in everyday Tampa life means cards that work the first time they get used, network status confirmed before the visit, prescriptions filling at the price you were quoted, and a household budget still doing its job.
The Slow Bleed of a Tampa Plan Picked on Autopilot
Auto-renewing the same card you carried last year rarely shows up as a single bad day. It usually shows up as a string of small, easy-to-miss losses. The dermatologist your spouse has seen for years quietly moves to out-of-network status when the carrier renegotiates and the visits start billing at three times what you budgeted. A specialty pharmacy ships a quarterly medication that lands in a higher formulary tier than it occupied in December. An emergency room visit for a kid’s broken arm comes back coded fine, but the orthopedic follow-up is billed under a contract your plan never included.
These outcomes are not abstractions; they are the very misses a thorough review intercepts before a Tampa household commits. The cost of doing nothing rarely lands at zero. The cost of choosing on purpose is a single conversation.
From South Tampa to New Tampa and Every Neighborhood Sofia Hears From
Conversations land from across the Tampa map — South Tampa and Hyde Park households framing plans around Tampa General and Bayshore-area pediatricians, Davis Islands residents pairing coverage with their existing TGH specialists, Westshore and International Plaza professionals weighing employer plans against the marketplace, Channelside and Ybor City young couples deciding between two single plans or a shared household one, Seminole Heights and Tampa Heights freelancers building HSA-compatible setups around uneven income, Carrollwood and Citrus Park families verifying pediatric and family practice participation, New Tampa and USF-area households checking AdventHealth and James A. Haley access, Westchase and Town ‘N’ Country contractors balancing Veterans Expressway commutes against in-network reach, and MacDill-adjacent service members and retirees building bridges from TRICARE into civilian coverage.
The complete list of categories Sofia handles lives on the Gold Standard insurance services hub, the natural next stop. To read what Tampa neighbors have shared about working with her, the client testimonials page covers it directly.
What Changes When a Tampa Plan Question Crosses the County Line
Florida sets its marketplace rating areas county by county, so the menu of plans attached to an address can change the moment that address sits outside Hillsborough. Two households with the same income and the same doctors in mind will not always see the same carrier field — availability turns on carrier, ZIP or county, and eligibility. Sofia starts every comparison from the address on the application rather than from a plan name, because that is the input the rest of the math hangs on.
Networks Redraw Themselves Faster Than the County Line Does
Hospital access is the piece that shifts first. Coverage framed around Tampa General or AdventHealth Tampa reads one way for a household inside the city and another once daily care leans toward the east-county facilities and specialists that shape a shortlist for Brandon health insurance conversations, or toward the family practices and pediatric offices along the US-301 corridor that come up whenever coverage help for Riverview households is the starting point. The plan structure follows that map: a tighter HMO network can be the sensible pick when care stays close to home, while a household splitting its providers across two ends of the county usually wants to see what a PPO or POS structure allows before ruling either out.
Coverage That Has to Work on Both Sides of the Bay
Crossing into Pinellas is a bigger change than the drive suggests. Because the rating area changes at the county line, a Tampa household weighing a job, a move, or a specialist referral toward health coverage guidance for St. Petersburg is looking at a separate carrier field, not the same plans priced differently. The practical checks are the same three every time: confirm the providers you actually use are participating under the exact plan name rather than the carrier brand, confirm each prescription against that plan’s drug list, and confirm what the plan asks of you before it starts paying. Run in that order, a two-county question settles without guesswork.
What Working With a Tampa Health Insurance Consultant Looks Like
Tampa is big enough that no two households shop from the same starting line — a South Tampa family, a New Tampa commuter, a Westshore professional between jobs, and a MacDill-area household are all weighing different networks, budgets, and reasons for being in the market for an insurance plan at all. A consultant’s value in a city this size is triage: cutting a sprawling carrier menu down to the health plan that fits one household. From the Gold Standard office, Sofia runs that triage through the two anchors of any insurance plan — the hospitals a household uses and the year its coverage has to absorb.
The Hospital Question Behind Every Tampa Plan
In Tampa, the network question is really a hospital question, so before any health plan is called a fit the carrier network gets checked against the specific facilities and doctors a household already depends on across a spread-out city.
The Hospital Systems a Tampa Plan Has to Hold
- A household oriented toward Tampa General on Davis Islands lives inside a different footprint than one relying on AdventHealth Tampa.
- Cancer care routed through Moffitt sets its own network demands on the medical coverage.
- Households leaning on the clinics nearest USF need that access confirmed in-network.
- The same insurance plan can hold one system comfortably in its health coverage and keep another at a steeper tier.
Matching a Structure to a Spread-Out City
- PPO insurance plan: reaches a specialist anywhere from Davis Islands to USF without a referral, earning its higher share.
- EPO health plan: cuts the premium by declining out-of-network care short of an emergency.
- POS plan: keeps a home-base doctor with some room to roam.
- HMO health plan: holds the line on cost by running every referral through one coordinating doctor.
That single network verification is where most avoidable Tampa surprises get caught, long before a claim ever tests the medical coverage.
Pricing a Plan Against the Year It Has to Cover
A premium is one line; the year is the whole story. Each health policy gets projected across a realistic year of use — deductible, copays, prescription tiers, and an out-of-pocket ceiling that matters most the moment a household leans on the coverage. That work produces written deliverables a Tampa household can hold onto.
Cutting a Sprawling Carrier List to One Plan
Most clients arrive worn down by the size of the menu and leave with one insurance plan recommended, the logic for it on paper, a per-plan network read tied to the hospitals and doctors they use, and a formulary check matching maintenance prescriptions to the plan’s tier list.
South Tampa Close-In, New Tampa Far-Flung
A South Tampa household that stays close in often does fine on a tighter insurance plan, while a New Tampa family crossing the county for work and school needs health coverage with more reach. A dental or vision layer bolted onto the primary medical plan covers the rest of an active year.
Keeping Coverage Continuous Between Jobs
A job change opens a special-enrollment window that does not stay open long, so the written plan maps the enrollment route in play and the deductible math across the full year, with the headline premium set against honest out-of-pocket figures.
Between Jobs in a Big City
A common Tampa case runs on timing as much as network: a Westshore professional leaves one employer for another, and for a few weeks the household sits between group health plans with COBRA on the table and a decision to make.
A Westshore Job Ends
A Westshore professional leaves one employer for another, COBRA on the table, while the household weighs how soon the new employer’s health coverage begins and what the family needs in the meantime.
A Narrow Window Opens
The job change itself opens a special-enrollment window for a new insurance plan, but the stretch is narrow, and a consultant who flags the timing early keeps the medical coverage from lapsing between jobs.
An Individual Plan Bridges the Gap
An individual health plan bridges the gap with its network verified for Tampa General, AdventHealth, or Moffitt as needed, so a planned surgery or ongoing prescription never falls into an uncovered seam.
Questions Tampa Households Bring to Their Broker
How do I figure out the right health insurance in Florida for my Tampa household?
Our South Tampa household runs nearly everything through Tampa General — how do we keep that access when we switch plans?
I’m separating from MacDill and TRICARE is ending soon — how does the move to civilian coverage really work?
My income from a one-person Seminole Heights business rises and falls all year — can a health plan keep up with that?
I’m leaving a corporate role in Westchase and COBRA looks painful — what other options should I weigh?
Two of us share a Channelside place and both commute downtown — is one shared plan smarter than two separate ones?
What Tampa Neighbors Have Written After Working With Sofia
Sofie was incredible helping me obtain a personal insurance policy for myself and one for my 22-year-old daughter. She explained everything clearly, offered advice, answered questions and was always available. I would highly recommend working with her for your insurance needs.
Sofia is incredible! She helped my family and I find a great plan and I am incredibly grateful. She is extremely knowledgeable, kind, and very responsive. A true professional who truly cares about her clients. Thank you again, Sofia!
Sofia was absolutely fantastic to work with. She is incredibly knowledgeable, responsive, and took the time to explain all of my options in a clear, no-pressure way. Sofia made the entire insurance process easy and stress-free, which is rare and so appreciated. If you’re looking for someone trustworthy, professional, and genuinely invested in helping you, I can’t recommend Sofia enough!
Sofia was extremely patient, explained everything in detail and got me an amazing deal! Couldn’t be happier from start to finish she was truly exceptional.
Sofia was awesome to work with, and as everyone know, the insurance shopping experience is not for the faint of heart. As someone who works in healthcare- I even find it difficult to choose an insurance plan because it’s hard to understand all the nuances. Sofia made it easy for me by explaining everything thoroughly to me, prepping me for the call from the insurance agency and even had calls with me to nearly 10pm to accommodate my crazy work schedule. If you work with Sofia, I have full confidence she will get the job done!
Sofia was wonderful to work with. So helpful, knowledgeable, and made the whole process feel easy and stress-free. I truly appreciated her support and would highly recommend her.
I had the pleasure of working with Sofia Mavronasios to update health insurance for my 3 children. She is an outstanding and knowledgable representative for Gold Standard insurance and got me the best policies for my kids. She was always prompt and attentive to my phone calls and I highly recommend her if you need health insurance guidance.
Sofia worked very hard and diligently to help me. She kept in touch everyday. Getting insurance is hard but having someone there for every step took a lot of weight off my shoulders! I highly recommend working with Sofia to ease the stress!