Medical Insurance Brokers Serving Plant City, FL
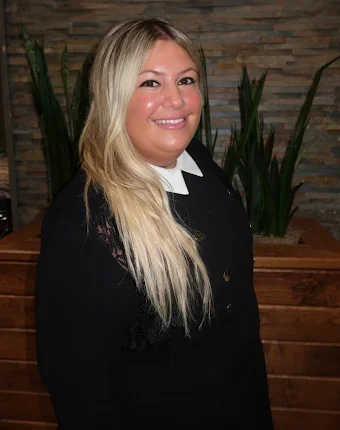
Strawberry country runs on its own clock — harvest stretches, a downtown that still knows its neighbors, and farm-to-family businesses that never fit a tidy corporate mold. A working medical insurance broker respects that instead of flattening it into one generic quote. Sofia at Gold Standard sits at the table with you, opens the available carriers that actually reach eastern Hillsborough, and says plainly which structure earns what it asks of your budget.
Looking up health insurance brokers in my area only gets you partway; the plans that surface for your household hinge on your Plant City ZIP, the available carriers writing here this season, and whichever mid-year enrollment door currently stands open for you. An independent health insurance agent reads all three before naming a fit.
The Snags That Slow Plant City Households Down
Most people read a page like this because a renewal letter, a growing family, or a leap into self-employment forced the question. Out here in east Hillsborough, three snags trip folks up more than the rest, and spotting yours clears most of the fog.
Networks Look Different East of the I-4 Exits
A carrier that contracts cleanly with South Florida Baptist one year can rework the deal the next, and the systems you reach off Jim Redman Parkway and Alexander Street are split across more than one network. Drug formularies reset with the new year. The sign-up window keeps its own calendar and waits for nobody.
The Hunch You Picked the Wrong Card
You can lock in a plan and still second-guess, somewhere along Park Road, whether the clinic near Walden Lake honors it. That hunch is reasonable — benefit summaries were not written to be cracked between a harvest shift and a school pickup, and one bad assumption rides along all year.
A Town Built on Hard Work Has Earned Coverage That Stays Out of the Way
Plant City runs on growers, tradespeople, downtown shop owners, and families putting down roots in the newer developments. Guarding the household should not be the toughest chore of the month. A steady guide across the table, carrier documents already open, turns the whole task from dread into a decision.
Why Strawberry-Country Families Trust an Independent Broker to Sort Their Coverage
The Questions Reaching This Health Insurance Advisor Echo Your Own
The calls into this corner of the county rhyme with one another — a grower near Trapnell whose income arrives in seasonal waves, a downtown shop owner weighing a first group plan for two employees, a Walden Lake retiree pairing Medicare with a supplement that holds, a family freshly arrived in a Cork-area subdivision from up north with no read on the available carriers. Each lands on a workable answer, and not one is new ground for a health insurance advisor who fields them weekly.
You set the pace. The recommendation arrives after your questions are settled, never before. A first call assumes nothing about whether you enroll at the end — that is the difference an independent health insurance agent brings over a single-carrier sales desk.
What Holds Up Every Recommendation This Broker Makes
- A Florida health-coverage license run out of the Gold Standard office on East Hillsborough Avenue, a straight shot west on I-4 from strawberry country.
- A finance background ahead of insurance, which is why the real-use cost — the monthly line, the deductible you meet first, the annual ceiling — gets framed against your household’s actual numbers, not a brochure average.
- Contracts spanning a range of available carriers rather than one company’s shelf, the mark of an independent health insurance agent rather than a captive rep.
- A working roster of Plant City, Dover, Cork, and Lakeland-edge households this broker has already walked through the same decision.
- Client reviews holding a 5.0 average, plus a direct number a real person still answers once the ink is dry.
Three Talks Take Plant City Coverage From Maybe to Member ID
From the outside the process looks like a maze. Once it is spelled out, the path is just three brief talks — nothing tucked away, no extra stage hiding at the back.
Sketch Out Who Needs Covering and Which Care Stays
Everyone the policy must name, the participating providers worth keeping, the prescriptions on standing order, and a monthly number that leaves room for the truck, the land, and the kids’ activities. One plain talk with your broker, no obligation riding on it.
Audit the Available Carriers That Truly Reach Your Plant City Address
Lay HMO, EPO, PPO, and POS options that truly reach your address side by side — participating providers verified, the medication list matched to each formulary, and the honest real-use cost dragged out from under the marketing by a broker who does this daily.
Switch the Card Live With Every Doctor Pinned Down First
Sign on through the enrollment door that matches your situation — open season or a qualifying mid-year enrollment door — collect a month-one rundown for using the card at South Florida Baptist or a Tampa system, and keep your broker’s direct line for whatever the rest of the year sends your way.
Swap a Browser Full of Tabs for One Plain Recommendation
A quick session with Sofia ends in a written recommendation shaped around your Plant City household — enroll right then or take a week to hash it out with whoever shares the decision.
Plans and Coverage Plant City Households Reach For First
Plan Types
CoreCoverage Needs
PopularA Plain Plant City Week When the Coverage Fits
A downtown family brings a child to a clinic for a sports physical, slides an ID card across the counter, and pays the copay Sofia named ahead of time — no guesswork about which hospital network the plan is actually tied to. A self-employed grower near Cork refills a maintenance prescription the same week the harvest check clears, with no formulary jolt waiting at the register. A Walden Lake couple keeps an annual checkup at a practice already verified in-network before coverage went live, and the visit passes without a billing snag. A household new to a Midway subdivision runs a first urgent-care trip through a plan matched to their doctors from the start. To see the complete range behind those quiet wins, the range of coverage Sofia handles lists it in full.
That calm is what a deliberate plan buys you — cards that work on the first try, networks pinned down ahead of time, prescriptions ringing up at the quoted figure, and a budget that still lands where you planned.
The Quiet Toll of a Plant City Plan Left on Cruise Control
Renewing last year’s card without a second look rarely detonates all at once. It bleeds out across the months in small, easy-to-miss charges. The specialist your spouse has counted on for years quietly drops to out-of-network when the contract is redone, and a routine visit lands at several times what you expected. A medication that rode comfortably in one tier through December climbs to a pricier one by planting season. A weekend urgent-care run gets paid, but the outside radiologist who read the scan bills under a contract the plan never carried.
Not a word of that is invented; it is the exact slip a thorough look-through surfaces before anyone here signs the paperwork. Sitting still is seldom free; deciding on purpose takes an afternoon, no more.
Downtown, Walden Lake, Cork, and the Trapnell Stretch
Plan talks come in from every part of town — downtown and historic-district households lining coverage up with South Florida Baptist providers, Walden Lake retirees pairing Medicare with a supplement that holds, growers and trades around Trapnell and Turkey Creek Road shaping plans that absorb a seasonal income, Cork and Midway families verifying pediatric and family-practice participation, and Lakeland-edge commuters splitting an I-4 drive against in-network reach near home. However your days run, the talk holds its focus on the way your household truly lives out here in strawberry country.
Once you would like to claim a time, the scheduling page opens the quickest door to Sofia’s calendar.
How a Plant City Medical Insurance Broker Sorts Your Choices in Plain Language
Plant City runs on a calendar most insurance brochures never account for. Strawberry season swells the work and the income from late fall through spring, then the rhythm changes, and growers, packers, drivers, and the small businesses around them carry a paycheck that moves with the harvest. A medical insurance broker who works this part of east Hillsborough builds the review around how a household actually earns and spends across a year — not a generic twelve-month assumption — then finds the insurance plan whose health coverage holds steady whether the season is running hot or winding down.
Why a Broker Beats a Portal Guess in Strawberry Country
So many households here are self-employed or work seasonal, agricultural jobs with no benefits desk — the health insurance plan is bought and owned, not handed over. A portal shows a wall of plans and leaves you sorting the health coverage at midnight; a broker carries that sorting instead, starting with the doctors and reading the money across the whole season.
What a Broker Checks Before Naming a Plan
- The doctors first: does the carrier network behind the health plan keep the primary-care office near downtown, the specialists at South Florida Baptist Hospital, and the pharmacy out toward Walden Lake or along the James L. Redman corridor?
- An insurance plan that drops a provider a household depends on has already failed the medical coverage test, whatever its premium looks like.
- The money read across the whole season: each health plan’s premium, deductible, copays, and prescription tiers projected over a realistic year, with the deductible arithmetic shown plainly.
- Special-enrollment mapped for income swings, so a special-enrollment change can reopen the right health coverage mid-year when the work changes.
The Plan Lanes That Fit a Seasonal Household
- HMO health plan: anchors care to a primary doctor who handles referrals and holds the premium steadiest — a clean fit when health coverage centers on a clinic in town.
- PPO insurance plan: trades a higher share for reach to Tampa or Lakeland providers without a referral when the medical coverage spans counties.
- POS plan: blends the two for a home-base doctor plus some out-of-network reach in the health coverage.
- Small-business group health plan: for a Plant City operation covering a crew under one roof rather than sending each worker to shop individual coverage alone.
A portal hands you the wall of plans and leaves you to sort it at midnight; a broker carries that sorting. A health plan that drops a provider you depend on has already failed the test — whatever the premium looks like.
The Coverage Lanes a Plant City Household Opens First
None of those lanes is automatically right; the fit depends on how a household lives and works the season. Pick the wrong insurance plan and the cost lands at the worst time — which is exactly what a careful review reads for before anyone signs.
A Paycheck That Tracks the Harvest
The income here is honest but uneven, climbing in peak season and thinning after, so the goal is medical coverage that stays even when the paycheck is not — a health policy steady on the card whether the strawberries are running or resting.
A Deductible That Empties a Peak-Season Cushion
A mismatched health plan can read cheap on premium and still leave the medical coverage exposed — a deductible that empties a peak-season cushion, or a network that pushes a routine visit out of coverage during the busiest stretch of the year.
One Plan You Actually Understand
A careful review leaves one recommended insurance plan, a written reason it won, a formulary check on every maintenance prescription, a dental or vision layer over the primary medical plan, and a standing line back to Sofia.
Reading a Plan Across a Harvest Year
Walk a Plant City health insurance plan through an actual harvest year and the fit becomes obvious. The review reads the insurance plan against the leaner stretch from the start, not the flush one, so the medical coverage stays predictable across the whole calendar.
The Harvest Runs and the Premium Is Easy
Through the busy stretch the work is steady, the premium on the insurance plan is easy to carry, and the health coverage barely registers — the flush months rarely test a health policy at all.
The Off-Months Test the Same Policy
When the income thins, the same policy still has to hold a maintenance refill, a routine visit at South Florida Baptist Hospital, and whatever the season’s work did to a back or a knee — the off-months are where a plan built only on peak earnings strains.
A Life Change Reopens the Coverage
A grower whose hours fall may find a life change has reopened the right health coverage mid-year through special-enrollment, so a household is not stuck riding out an insurance plan that stopped fitting — and a dental or vision layer fills in the rest a working household actually uses.
Plant City Health Insurance Broker Questions Sofia Hears at the Table
My grower income lands in seasonal waves — can a medical insurance broker build coverage that survives a feast-then-famine year?
My downtown shop carries just two people on payroll — would a broker who works independent of any single carrier say a group plan is worth it?
South Florida Baptist handles most of our care — how does a broker keep that hospital reachable under a new plan?
I just went self-employed after a Lakeland job ended — what does a health insurance advisor put in place of the plan I lost?
Fresh off a move into the Midway area — how do health insurance brokers in my area tell which Florida carriers keep the doctors we already see?
Why does health insurance in Florida cost what it does — what actually drives the number a Plant City household sees?
What Plant City Clients Say After Meeting With Sofia
Sofie was incredible helping me obtain a personal insurance policy for myself and one for my 22-year-old daughter. She explained everything clearly, offered advice, answered questions and was always available. I would highly recommend working with her for your insurance needs.
Sofia is incredible! She helped my family and I find a great plan and I am incredibly grateful. She is extremely knowledgeable, kind, and very responsive. A true professional who truly cares about her clients. Thank you again, Sofia!
Sofia was absolutely fantastic to work with. She is incredibly knowledgeable, responsive, and took the time to explain all of my options in a clear, no-pressure way. Sofia made the entire insurance process easy and stress-free, which is rare and so appreciated. If you’re looking for someone trustworthy, professional, and genuinely invested in helping you, I can’t recommend Sofia enough!
Sofia was extremely patient, explained everything in detail and got me an amazing deal! Couldn’t be happier from start to finish she was truly exceptional.
Sofia was awesome to work with, and as everyone know, the insurance shopping experience is not for the faint of heart. As someone who works in healthcare- I even find it difficult to choose an insurance plan because it’s hard to understand all the nuances. Sofia made it easy for me by explaining everything thoroughly to me, prepping me for the call from the insurance agency and even had calls with me to nearly 10pm to accommodate my crazy work schedule. If you work with Sofia, I have full confidence she will get the job done!
Sofia was wonderful to work with. So helpful, knowledgeable, and made the whole process feel easy and stress-free. I truly appreciated her support and would highly recommend her.
I had the pleasure of working with Sofia Mavronasios to update health insurance for my 3 children. She is an outstanding and knowledgable representative for Gold Standard insurance and got me the best policies for my kids. She was always prompt and attentive to my phone calls and I highly recommend her if you need health insurance guidance.
Sofia worked very hard and diligently to help me. She kept in touch everyday. Getting insurance is hard but having someone there for every step took a lot of weight off my shoulders! I highly recommend working with Sofia to ease the stress!